First Hurdle for Haetsal Loan Card Issuance Is Completing Three Mandatory Education Courses — Full Overview of Eligibility and Usage Restrictions
## Who Is the Haetsal Loan Card For? Consider an office worker with a KCB credit score of 820 who is rejected when trying to get a new credit card. This scenario clearly shows who the Haetsal Loan Card from the Korea Inclusive Finance Agency (KINFA, Seo Geum-won) is designed for. This score falls u
Who Is the Haetsal Loan Card For?
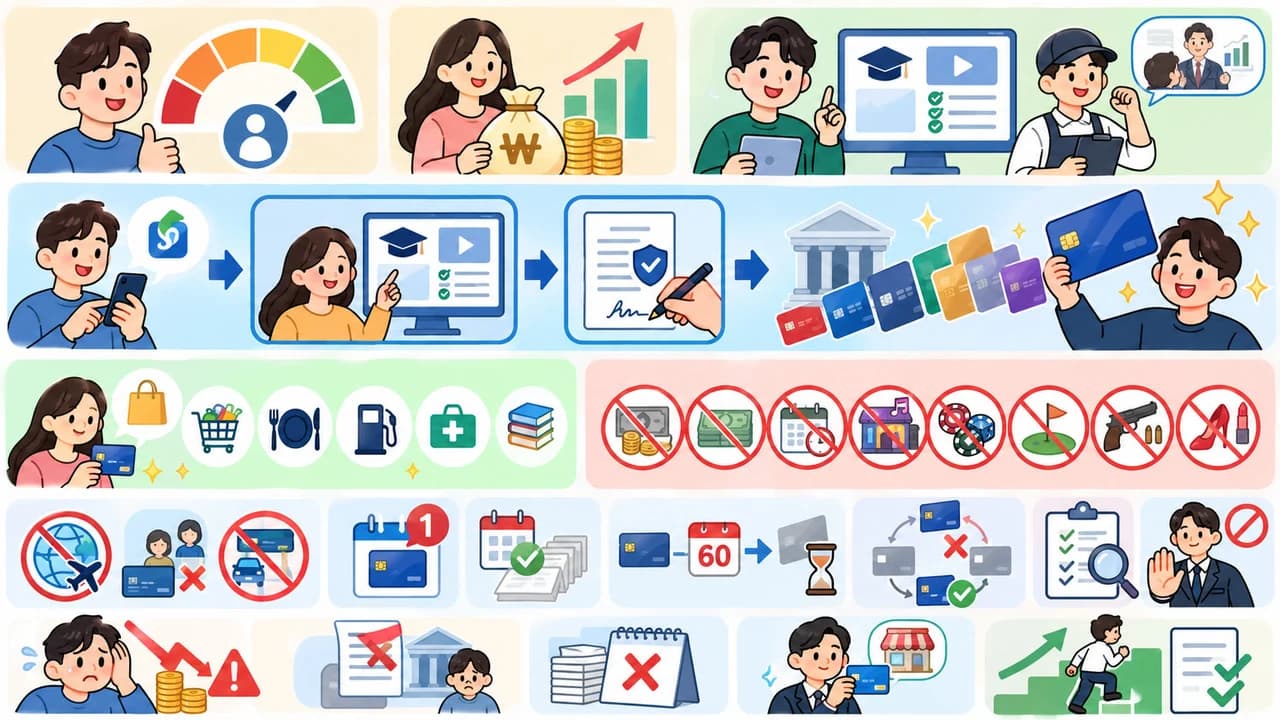
Consider an office worker with a KCB credit score of 820 who is rejected when trying to get a new credit card. This scenario clearly shows who the Haetsal Loan Card from the Korea Inclusive Finance Agency (KINFA, Seo Geum-won) is designed for. This score falls under the KCB 875-point-or-below threshold set by KINFA as of April 1, 2026. Under the NICE standard, those scoring 889 or below are eligible, and whichever of the two credit bureau scores is more favorable to the user is applied. Those in the bottom 50% of credit standings with an annual disposable income of at least 6 million won meet the basic qualifications.
The First Hurdle: Completing Three Mandatory Education Courses
However, meeting the eligibility criteria does not immediately result in a card. One must first obtain KINFA's guarantee, and to conclude the guarantee agreement, one must complete education or consulting. Completion is automatically verified electronically, and without it, the process stops at the guarantee agreement stage.
The application process begins by requesting a guarantee through the KINFA app. Afterwards, one of two methods must be chosen and completed.
First, complete three or more mandatory courses of the 'Haetsal Loan Card User Education' on KINFA's financial education portal. After registering on the portal, one can take courses under the online education, loan user education, and Haetsal Loan Card menus. Completion certificates can be checked under the online learning status in My Page.
Second, receive KINFA's small business consulting. After identity verification, choose one field among tax, labor, legal, or health consulting and receive a non-face-to-face consultation. Completion is processed within three business days of the consultation date. If the consultation takes place on a Friday, weekends are excluded from business days, so processing may take until the following Wednesday.
After Concluding the Guarantee Agreement, Apply to a Card Company for Issuance
Once completion is verified, reconnect to the KINFA app and conclude the guarantee agreement. After the agreement is concluded, apply for issuance with a card company. There are eight contracted card companies: Lotte, Samsung, Shinhan, Woori, Hana, Hyundai, KB Kookmin, and NH Nonghyup. Application methods, annual fees, and additional benefits vary by company and must be checked separately in KINFA's 'Contracted Card Company Issuance Application Guide'; the specific annual fee levels are not stated in this guidance material.
Usage Restrictions Different from Regular Credit Cards
The biggest difference from regular credit cards is the scope of use. Cash advances, card loans, and revolving credit are unavailable, and payment deferrals and installment payments of billed amounts are blocked. Installment purchases are limited to a maximum of six months.
Entertainment and gambling businesses, golf courses, firearms retailers, adult product stores, and some no-signature payments are also subject to usage restrictions. The scope of entertainment and gambling businesses follows the same standards as the national relief funds (disaster relief funds), but since card companies classify business types differently, actual payment availability may vary.
It should also be noted that this is a domestic-only card that cannot be used for overseas payments. Family cards and postpaid Hi-Pass credit cards are not issued. Each person is limited to one card from one card company, and the card company cannot be changed during the guarantee period. The card usage limit is managed by the card company within the guarantee limit.
Exclusions and Cautions for Small Business Owners
The scope of those who may be excluded due to credit status is also defined. Holders of public information records are, in principle, ineligible. However, among those undergoing the Credit Counseling & Recovery Service's individual workout, personal rehabilitation, or the New Start Fund's debt adjustment, those who have repaid without delinquency for six installments (six months), excluding grace periods, may apply. Those in payment deferment are excluded.
Small business owners should be careful when choosing a card company. Those who have already received an individual Haetsal Loan Card may receive a special-exception Haetsal Loan Card for small business owners from card companies other than the one already used. This is why one should consider future plans for a special-exception card when choosing an individual card company.
Even with all qualifications met, one may still be rejected. One must pass both KINFA's credit guarantee review and the card company's issuance review, and if one holds a dormant card at the card company applied to, issuance may be rejected. Before applying, it is necessary to check whether any unused cards remain with that card company. ## Repayment Responsibility and Reapplication Conditions
Repayment responsibility is no different from regular cards. If usage payments are not made on time, delinquency records are registered, and KINFA, after repaying the card company on the user's behalf, exercises its right of subrogation against the user. This means that even a card issued with a guarantee does not eliminate delinquency liability. To reapply after canceling a card, 60 days must pass from the cancellation date.
Three Things to Check Going Forward
Three matters should be checked going forward. The credit score thresholds were presented as of April 1, 2026, and may be adjusted later. Annual fees and benefits by card company must be compared separately through the contracted card companies' guides. The specific amounts of the guarantee limit and card usage limit are not stated in this guidance material and must be confirmed during the application process.
[This article was written based on official guidance from the Korea Inclusive Finance Agency, and eligibility, procedures, and usage conditions may change according to the agency's and card companies' circumstances. Before actually applying, be sure to check the latest guidance from the KINFA app, the financial education portal, or the contracted card companies. AI assisted in part.]
CBC Globe publishes verified stories with editorial review, source checks, and tenant-specific publication standards.
Related Articles
KOSDAQ Surges 4.48% to Close at 894.29... Rino Industrial Up 10.90%, Biggest Gain Among Top-Market-Cap Stocks

[Breaking] NY Markets Close Slightly Higher Despite 10-Year Treasury Yield Spiking to 5.34% Intraday...S&P 500 Up 0.19%
KOSPI Rises 1.95% to Recover 6,970 Level... 'Samtecnics' in Focus as Market Eyes Reclaim of 7,000