SK Hynix Target Price Maintained at 310,000 Won... Mirae Asset: "HBM and DRAM Effectively Allocated Through 2029"
Attention in the securities industry is focusing on SK Hynix's (000660) mid- to long-term earnings growth potential. With high-bandwidth memory (HBM) and conventional DRAM supply shortages expected to persist for an extended period, how much customer volume the company has secured through 2029 has e
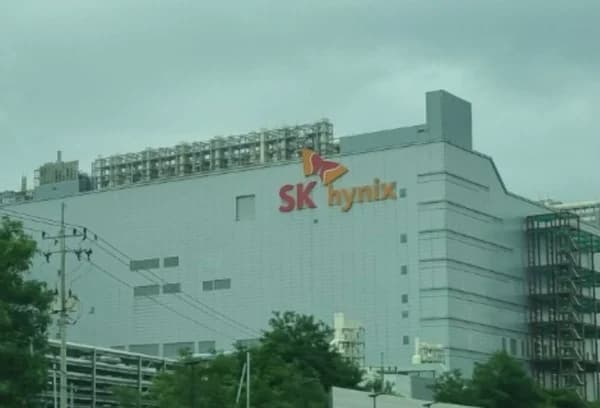
Attention in the securities industry is focusing on SK Hynix's (000660) mid- to long-term earnings growth potential. With high-bandwidth memory (HBM) and conventional DRAM supply shortages expected to persist for an extended period, how much customer volume the company has secured through 2029 has emerged as a key variable for its performance.
Mirae Asset Securities Maintains Target Price at 310,000 Won, Raises Earnings Forecasts
Mirae Asset Securities maintained its target price for SK Hynix at 310,000 won, while raising its operating profit forecasts for both the fourth quarter of this year and next year, predicting that the memory industry's supply-demand structure will remain solid over the mid to long term.
Specifically, Mirae Asset Securities set its Q4 2026 operating profit forecast for SK Hynix at 108 trillion won, up 30% from the previous quarter and a 6% upward adjustment from its earlier estimate. Its 2027 operating profit forecast was raised to 489 trillion won, up 69% year-on-year and 14% higher than the previous estimate.
Production capacity expansion was also cited as a key driver of earnings growth. In the fourth quarter of this year, DRAM bit growth (B/G, the rate of increase in shipments measured in bits) is expected to rise by the mid-20% range quarter-on-quarter, aided by the expansion of the 1c process node and ramped-up operation of the M15X production facility.
"100 Trillion Won Shareholder Return Plan for 2026... Key Is Confidence in Demand Stability"
Notably, Mirae Asset Securities paid close attention to SK Hynix's mid- to long-term memory demand outlook. SK Hynix is reported to have presented a shareholder return plan worth 100 trillion won for 2026. Mirae Asset placed greater significance on the fact that this signaled confidence in demand stability through 2029, rather than the expansion of shareholder returns itself.
Supply Shortage to Last Until 2030... LTA Volumes to Account for Over 50% of Production Capacity
The industry structure, in which the memory supply shortage is unlikely to be resolved in the short term, also warrants attention. Analysts note that as the technical difficulty of advanced semiconductor manufacturing processes rises and the time required from building new production facilities to actual mass production lengthens, constraints on supply expansion may emerge. On the basis of these structural factors, Mirae Asset Securities forecast that the memory supply shortage will continue through 2030.
Long-term agreement (LTA) volumes are also an important point. Volumes under long-term supply agreements for 2027-2028 are expected to account for more than 50% of total production capacity. Including volumes currently under negotiation, DRAM and HBM production volumes through 2029 are effectively already allocated to customers.
HBM Production Expansion a Variable Tightening Conventional DRAM Supply
The impact of HBM production expansion on conventional DRAM supply is also a point of interest. As HBM profitability improves, semiconductor manufacturers have greater incentives to increase HBM production. However, the fact that expanding HBM production may reduce the capacity available for conventional DRAM is a variable. Mirae Asset Securities expects the high rate of capacity conversion driven by HBM production expansion to limit the supply capacity of conventional DRAM, thereby acting as a factor sustaining tight supply-demand conditions in the DRAM market.
Ultimately, the analysis suggests that the key variables in assessing SK Hynix's future performance go beyond simple volume growth, and lie in how long the improvement in HBM profitability and the shortage of conventional DRAM supply will persist.
SK Group Ranks 9th in October Netizens' Awards Corporate Category... Ranking Trend Draws Attention
These growth expectations for the semiconductor business also connect with broader perceptions of SK Group's corporate competitiveness. As of the afternoon of the 29th, SK Group, which counts SK Hynix among its major affiliates, ranked 9th in the corporate category of the October Netizens' Awards. With the mid- to long-term growth potential of its semiconductor business drawing attention, how public interest in the company will affect the awards rankings and what ranking trajectory it will show in the remaining period are points of interest. It remains to be seen how assessments by those focused on the company's technological capabilities and future growth will be reflected in the awards.
Forecasts Are Securities Firm Estimates... Results May Vary Depending on Variables
However, the operating profit forecasts for 2027 onward and the expectation of a supply shortage through 2030 reflect Mirae Asset Securities' estimates. Actual results may vary depending on semiconductor demand, customer investment plans, the pace of capacity expansion, and memory prices.
[This article is for informational purposes based on corporate analysis and does not recommend the purchase or sale of any specific stock. Target prices and earnings forecasts are securities firm estimates and may differ from actual results. AI provided partial assistance.]
CBC Globe publishes verified stories with editorial review, source checks, and tenant-specific publication standards.
Related Articles
Jung Dong-won's Youthful Face in 'Nui' Stage Revisited... Lim Young-woong, Young Tak, Lee Chan-won, Jang Min-ho's 'Call Center of Love' TOP6 Joint Performance
Globe Netizen Awards Film Grand Prize Voting Status: Jeon Do-yeon's 'Possible Love' Leads with 71.7%... Can Byeon Woo-seok and Kim Hye-yoon Pull Off a Comeback?
Analyzing RESCENE's Universe: A K-pop Concept Expanding Through the Narrative of 'Memory'
