Era of 200 Trillion Won in Pension Savings… 16.5% Tax on Mid-Term Withdrawals, Expected Pension Amounts May Change
Pensions saved over many years for retirement preparation may turn out to differ from expectations at the actual payout stage. The pension amount communicated at the time of enrollment is not necessarily guaranteed, and the actual amount received can vary depending on how taxation is applied during
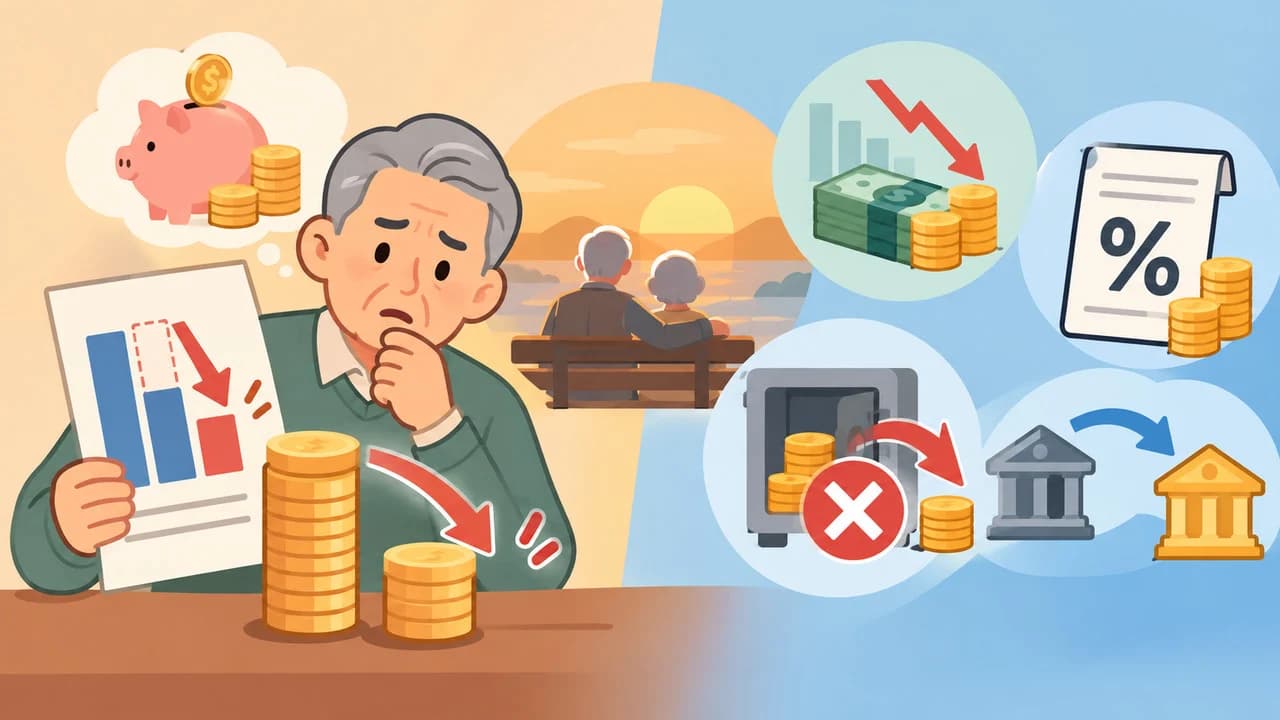
Pensions saved over many years for retirement preparation may turn out to differ from expectations at the actual payout stage. The pension amount communicated at the time of enrollment is not necessarily guaranteed, and the actual amount received can vary depending on how taxation is applied during mid-term withdrawals of accumulated funds or the pension receipt process.
The Financial Supervisory Service announced on the 21st a guide titled "Consumer Precautions for a Stable Retirement Life," which outlines contract conditions and tax issues that pension savings subscribers are likely to overlook.
■ Pension Savings Balance Exceeds 200 Trillion Won… Disputes Continue
The guide comes as the pension savings market grows rapidly. As of the second quarter of this year, pension savings balances surpassed 200 trillion won. As movements to prepare retirement income independently continue, funds accumulated in pension savings are increasing.
However, separate from market size, complaints and disputes among consumers using pension products continue. This is because differences arise between the conditions understood at the time of enrollment and what is confirmed during the actual pension payout process.
■ "Expected Pension Amounts Are Not Guaranteed"… They Vary with Interest Rates and Dividends
A representative issue is the gap in perception regarding expected pension amounts. The pension amount shown by insurance companies in enrollment proposals is an estimate calculated based on certain assumed interest rates and conditions. If consumers understand this as an amount that will definitely be paid in the future, differences may arise at the actual pension receipt stage.
Interest-rate-linked pension savings insurance is a typical product where such differences can occur, because the applicable interest rate at the time of contract signing is not fixed for the entire enrollment period. If the applicable rate changes after enrollment, the pension amount is affected, so even if the initially communicated expected pension amount was high, the actual payout may differ due to subsequent rate changes.
Similar problems can occur with insurance products that include dividends. For participating pension savings insurance, dividends vary depending on the insurance company's business performance, so the expected dividends reflected in the enrollment proposal cannot be assumed to remain the same at the time of actual payment.
The FSS emphasized that consumers should understand under what conditions the amounts were calculated, rather than focusing on the figures written in the enrollment proposal itself.
■ Mid-Term Withdrawals Subject to 16.5% Other Income Tax in Principle… "Submit Evidence Within 6 Months"
Before receiving pension payments, one must first check the tax burden of withdrawing accumulated funds. Mid-term withdrawals from a pension savings account are subject to a 16.5% other income tax in principle. However, if the withdrawal qualifies as an unavoidable circumstance recognized under relevant regulations, a pension income tax of 3.3% to 5.5% applies.
Being recognized as an unavoidable withdrawal requires more than just having a qualifying reason. Related documents must be submitted within the designated period, and the FSS advised that evidence must be submitted within six months. Depending on the withdrawal reason, limits may also apply to the amount that can be withdrawn. Therefore, subscribers planning to use accumulated funds midway need to check not only withdrawal eligibility but also tax application criteria and required documents.
■ Payment Amounts Can Change Even After Pension Receipt Begins
Even after pension payments begin, the received amount is not always maintained at a constant level. If the investment performance of funds accumulated in the pension savings account changes, the pension amount paid can also change. Situations where investment returns increase or decrease can affect the actual pension amount received. How taxes are calculated is also a factor determining the received amount.
Pension savings subscribers need to confirm whether the amounts they expect to receive in the future are actually guaranteed, what taxes are imposed on mid-term withdrawals, and whether payment amounts can change even after pension receipt begins. Accurately understanding contract terms is becoming increasingly important in the process of preparing retirement funds.
[This article was written based on the "Consumer Precautions Guide for a Stable Retirement Life" announced by the Financial Supervisory Service on October 21, 2026. Pension amounts and taxes may vary depending on the product and individual conditions, so specific details should be confirmed through the relevant financial institution and regulations. AI provided partial assistance.]
CBC Globe publishes verified stories with editorial review, source checks, and tenant-specific publication standards.
Related Articles
[Breaking] New York Stock Market Closes Higher Across All Three Major Indexes... Nasdaq Up 1.05%, S&P 500 Nears Record High, SpaceX Turns to Profit in Q3
[Breaking] U.S. Tech Stocks Mostly Higher in New York Market... SpaceX Surges 7.79%, Nvidia Breaks $221
Meta's Q3 Earnings Report Imminent... Revenue of $63.34 Billion Forecast with 17% Net Profit Decline; 6.3% Stock Price Volatility in Focus